FIRE Calculator
A FIRE calculator answers two questions: how large a portfolio you need for financial independence (your annual expenses divided by a safe withdrawal rate) and how long it will take to get there. Spending $60,000 a year at a 4% withdrawal rate puts the target at $1,500,000, about 20.4 years away when saving $2,000/month from a $100,000 start at 7%.
Your Path to Financial Independence
- Your FI number
- $1,500,000
- $60,000 ÷ 4% withdrawal rate
- Years to reach it
- 20.4 years
- from $100,000, saving $2,000/month at 7%
At a 4% withdrawal rate, a portfolio of $1,500,000 supports $60,000 of annual spending in its first year of withdrawals.
What is the 4% rule?
The 4% rule says a retiree who withdraws 4% of a diversified portfolio in the first year, then adjusts that dollar amount for inflation annually, has historically had a high probability of the money lasting at least 30 years. Flip it around and it becomes a target: sustainable spending × 25 = the portfolio you need, which is exactly what this calculator computes. Spending $60,000 means aiming for $1,500,000; every additional $1,000 of annual spending adds $25,000 to the target, which is why the FIRE community obsesses at least as much over expenses as over returns.
Where does the rule come from?
The 4% rule grew out of research in the 1990s on "safe withdrawal rates," most famously a study by finance professors at Trinity University that back-tested various withdrawal percentages against decades of historical U.S. stock and bond returns, checking how often each rate would have survived a 30-year retirement. Around 4%, the historical success rates were high enough that the figure became the community's default planning anchor. It's an empirical summary of one country's past markets, though: a very useful rule of thumb, not a law of nature.
What the rule doesn't promise
Treat the output here as a well-grounded target, not a guarantee, because the 4% framework has known soft spots worth weighing together:
- Sequence-of-returns risk. Two retirements with the same average return can end differently if the bad years come first: early losses plus withdrawals compound against you in a way averages hide.
- The 30-year assumption. The historical evidence centers on 30-year retirements. Retiring at 40 means funding 50+ years, and many early retirees plan around 3–3.5% for that reason.
- Pre-tax vs post-tax. "Expenses" must mean spending including the taxes you'll owe on withdrawals; a target built on post-tax spending but funded with pre-tax accounts is quietly too small.
- Nominal projections. The years-to-FI figure grows your savings in nominal dollars, while your real target rises with your cost of living. Real returns are the honest yardstick for long horizons.
The inputs you control most
Of the four levers, monthly savings and expenses are the two you can actually steer, and expenses pull double duty, shrinking the target while freeing up savings. Returns are set by markets, and time does its best work when there's a lot of it, which is one more instance of the head start beating nearly everything else. If the years-to-FI number startles you, experiment with the expense field before the return field: cutting $6,000 a year of spending moves the target by $150,000 and adds $500/month to savings, a double effect no realistic rate change matches.
Solve your FI plan with Goal Mode
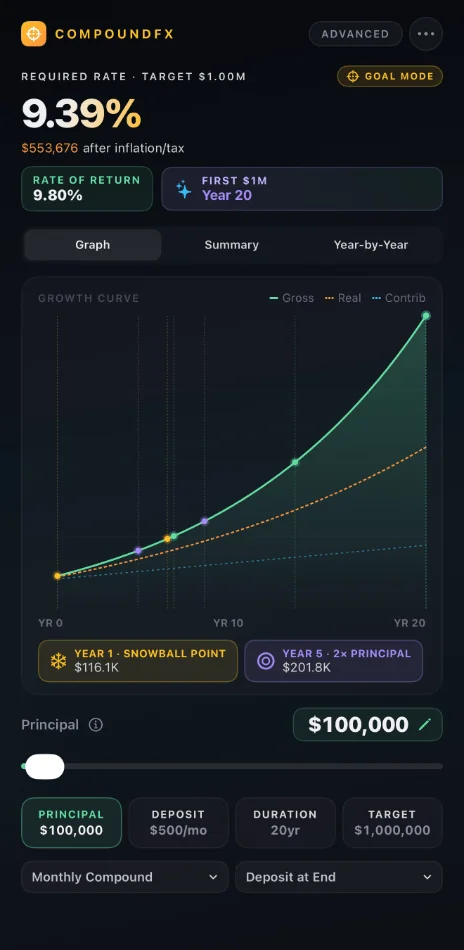
Your FI number is a goal with four moving parts: expenses, savings rate, return, and time. CompoundFX's Goal Mode lets you pin any three and solve the fourth, then keep every version as a saved scenario to compare.
See how Goal Mode works →
Free to download. Optional one-time Pro upgrade. No subscription.